
Cost-based pricing sets a product's price by adding a markup or target profit to its cost. It's one of the easiest ways to calculate a price, but a price that meets a financial target may still be too high for customers or too low to capture available demand.
This guide explains what cost-based pricing is, why it matters for retailers, the main types and formulas, and how the method works in real retail scenarios.
Key takeaways
- Cost-based pricing calculates selling prices from product costs plus a markup or target profit.
- The three cost-based pricing models are cost-plus pricing, markup pricing, and target return pricing.
- Cost-based pricing simplifies margin planning but overlooks customer demand, perceived value, and competitor prices.
- Enterprise retailers can use cost-based pricing to set guardrails while applying demand modeling to optimize prices above them.
What is cost-based pricing?
Cost-based pricing is a pricing method that starts with a product's cost and adds a markup to reach a selling price that covers costs and earns a target margin. The cost base can include purchase or production costs, freight, handling, labor, and overhead.
Retailers typically work from one of two cost bases:
- Full-cost pricing: The full unit cost, meaning variable costs plus an allocated share of fixed costs such as rent and warehousing, plus a markup.
- Direct-cost pricing: Variable costs only, which rise and fall with each unit sold, plus a markup.
The cost-based pricing formula establishes how much the retailer intends to recover per unit. Market and demand information then show whether that price is commercially realistic. Pricing and category managers also need to define what markups should recover, since the accounting cost of inventory and the full commercial cost of selling a product can differ.
One limitation is built in. The profit-maximizing price is where marginal revenue equals marginal cost, and that point depends on demand as well as cost. A price calculated from cost alone only lands there by coincidence.
How cost-based pricing differs from other pricing approaches
The cost-based pricing model relies on internal data, while other major retail pricing strategies, such as value-based, competition-based, and demand-based methods, take their cue from external factors like customer behavior, competitor prices, and demand patterns. The comparison section below covers each in detail.
The three types of cost-based pricing
There are three cost-based pricing methods. All three start from cost information, but the formulas change depending on which costs are included and how the profit objective is expressed. A clear pricing policy makes sure buyers, finance, and pricing analysts use the same method.
Type |
Formula |
Best-fit context |
Key limitation |
Cost-plus |
Unit cost × (1 + Markup on cost) |
Stable categories and private label with predictable costs |
Same markup regardless of demand |
Markup |
Purchase cost ÷ (1 − Markup on selling price) |
Large assortments managed against gross margin targets |
Margin target ignores willingness to pay |
Target return |
Variable cost per unit + (Fixed costs + Target return rate × Invested capital) ÷ Expected units sold |
Ranges that tie up significant inventory or space |
Assumes the forecast volume sells at the set price |
Table 1. The three types of cost-based pricing.
Cost-plus pricing
Cost-plus pricing calculates a selling price by adding a fixed percentage of the product's cost. For example, if the total unit cost is $80 and the markup is 25%, the selling price becomes $100.
The strength of this method is traceability: pricing and category teams can reconstruct any price from its cost and markup policy. Many retailers start with cost-plus pricing and move to more advanced methods as their business and market context grow more complex.
Markup pricing
Markup pricing sets profit as a percentage of the selling price, while cost-plus pricing sets it as a percentage of cost. Applied to the same product, the same percentage produces two different prices. A $40 product with a 30% markup on cost sells for $52; with a 30% markup on the selling price, it sells for about $57.14.
Markup pricing can support an economy pricing strategy, where retailers attract price-sensitive customers through competitive prices and high sales volume. Lower procurement and operating costs allow smaller markups while keeping margins acceptable, which makes the approach viable in highly competitive segments.
Target return pricing
Target return pricing, a cost-based pricing method that builds in invested capital, sets the selling price at a level that earns a defined return on the capital invested in a product or range. It incorporates fixed costs, variable costs, and the retailer's target profit.
For example, a range with a variable cost of $12 per unit, $50,000 in fixed costs, $200,000 of invested capital, and a 15% target return ($30,000) needs to sell 10,000 units at $20: $12 + ($50,000 + $30,000) ÷ 10,000.
Target return pricing suits buying decisions that commit capital up front, because it links the shelf price to the investment case buyers have already prepared. Its accuracy depends entirely on the sales forecast: if 10,000 units don't sell at $20, the return is missed. A pricing software solution like Competera uses demand modeling to forecast how sales volume may respond to different prices, so enterprise retailers can check whether a target-return price is realistic before implementing it.
The cost-based pricing formula
When calculating cost-based prices, retailers include all the relevant costs, such as purchase price, freight, handling, labor, and overhead. They use the result to set consistent prices and estimate each sale's contribution toward covering expenses and generating profit.
The general formula
The general cost-based pricing formula is:
Selling price = Unit cost × (1 + Markup rate)
Unit cost can be either full cost (variable costs plus allocated fixed costs) or direct cost (variable costs only), while the markup rate is the percentage added to the unit cost. Using the same cost base across categories keeps margin comparisons accurate.
If the objective is a specific gross margin, retailers need a different cost-based pricing formula:
Selling price = Unit cost ÷ (1 − Target gross margin rate)
For example, a $40 product with a 30% markup sells for $52, producing a gross margin of approximately 23.1%. To achieve a 30% gross margin, the retailer would need to charge approximately $57.14.
Worked cost-based pricing example: health and beauty retailer
A health and beauty retailer can use the cost-based pricing formula to price an own-brand moisturizer. Assume the unit cost is $10, including procurement, freight and handling, and overhead, with a 50% markup:
$10 × (1 + 50%) = $15
The product earns $5 per unit above its cost. That is a 50% markup on cost, which equals a 33.3% gross margin on the selling price. Knowing both figures matters when deciding how to increase profit margin across a range.
Cost-based pricing example: home furnishings retailer
A home furnishings retailer can use cost-based pricing to cover procurement and logistics expenses before setting a selling price. Consider an accent chair with a total unit cost of $150, including purchasing and freight. Applying a 40% markup gives:
$150 × (1 + 40%) = $210
At this price, the retailer earns $60 per unit above its stated costs, a gross margin of about 28.6%.
Furniture prices also depend on product design, customer preferences, and competitive alternatives. If comparable chairs sell for $190, the retailer must assess whether customers see enough added value to justify $210, or risk losing sales to lower-priced competitors.
Cost-based pricing vs. other pricing strategies
Each pricing approach starts from a different basis, which shapes both its strengths and its blind spots.
Approach |
Pricing basis |
Main advantages |
Main limitation |
Cost-based |
Product costs and markup |
Straightforward to calculate, auditable, needs little data |
Ignores customer behavior and market conditions |
Value-based |
Customer-perceived value |
Captures margin on differentiated products, reflects willingness to pay |
Value is hard to measure |
Competition-based |
Competitor selling prices |
Supports market positioning, protects price perception on KVIs |
May lead to margin erosion |
Table 2. Cost-based pricing compared with value-based and competition-based pricing.
Cost-based vs. value-based pricing
The difference between cost-based pricing and value-based pricing is whose perspective sets the price:
- Cost-based pricing uses the retailer's costs.
- Value-based pricing uses what customers are willing to pay for a product's benefits.
The gap is most evident in own-brand and exclusive products, where competitor prices are scarce or unavailable. In these cases, customers may pay more for differentiated features, perceived quality, or brand preference.
Two products could cost $20 to acquire but command different selling prices because customers value their benefits differently. Value-based pricing accounts for that difference, while cost information shows how profitable each price is.
Cost-based vs. competition-based pricing
Competition-based pricing positions each price against rival retailers, a step cost-based pricing skips. This method is particularly useful for key value items (KVIs), which customers frequently compare across retailers.
A retailer charging $12 for a widely available product may struggle to attract sales when comparable products consistently sell for $10. That's why the comparison between market-driven pricing and cost-plus pricing matters most for these products: retailers must weigh price gaps with competitors against the available margin to avoid pricing themselves out of the market.
Cost-based vs. demand-based pricing
Demand-based pricing sets prices according to how customers respond to price changes. Cost-based pricing calculates prices from financial inputs without estimating how demand will change at the resulting price.
While the cost-based pricing formula uses only internal cost data, demand-based pricing incorporates sales history and price elasticity to predict and recommend prices that support specific business objectives. As a result, demand-based pricing can align price more precisely with customer willingness to pay.
Advantages and limitations of cost-based pricing
The advantages and limitations of cost-based pricing stem from the same design choice: prices calculated from internal data alone. That makes prices fast to set and easy to defend, and it also leaves them blind to how shoppers and competitors respond.
Advantages
The advantages of cost-based pricing are mainly operational and financial:
- Fast to calculate: The cost-based pricing formula is simple and needs only internal inputs.
- Easy to audit: Pricing and category managers can reconstruct any price from its costs and markup policy.
- Cost visibility: The cost-based pricing model encourages retailers to identify all relevant procurement and operating expenses.
- Financial planning: Target markups provide a basis for estimating expected margins.
Limitations
The limitations of cost-based pricing come from its reliance on internal costs, which leaves out the factors that shape what customers will pay and how much they buy:
- Limited demand visibility: Two products with identical costs may respond very differently to the same price increase.
- Ignores competitor prices: A cost-based price can exceed what competitors charge for comparable products.
- Missed profits: Products with strong demand or few substitutes may support higher markups than a fixed markup suggests.
- Dependence on cost accuracy: Incomplete or outdated procurement, logistics, and overhead data can produce prices that fail to cover relevant expenses.
When cost-based pricing makes sense
Cost-based pricing makes sense when costs are predictable, competitors offer no close comparison, and the retailer has no demand data for the product. Common retail use cases include:
- New merchandise: Setting starting prices before sales history is available.
- Stable product categories: Applying consistent markup policies where unit costs are predictable.
- Margin planning: Calculating selling prices against defined cost recovery and profitability requirements.
Once a product builds sales history or becomes a comparison item, demand-aware or competitive pricing methods should take over as the main way to set its price, with cost-based calculations remaining as the floor.
Cost-based pricing in enterprise retail
In enterprise retail, cost-based pricing works best as a boundary for prices set by other price optimization models. Procurement costs set the necessary financial controls, while pricing decisions also account for product roles and demand signals.
Cost-based pricing as a margin floor
A margin floor sets the minimum margin a retailer will accept, which translates into a minimum price for each product. Cost-based pricing calculates that floor from the relevant costs and the required margin, which keeps recommended prices from falling below it during promotions and repricing.
From there, more advanced models evaluate potential prices above the floor using demand forecasts and commercial objectives, treating cost as one constraint in a broader process. For example, a retailer can apply competitive rules to KVIs and value-based reasoning to own-brand items.
Where cost-based pricing breaks down at enterprise scale
Cost-based pricing becomes less effective when enterprise retailers apply the same markup logic to every product, even though products play different roles in the assortment. Consider two products with the same unit cost:
- A frequently purchased KVI that influences price perception.
- An exclusive product with limited direct competition and lower price sensitivity.
Applying the same markup to both ignores their very different contributions to revenue and margin. Monitoring pricing KPIs, including gross margin, sell-through, and revenue, helps retailers see when standardized markups are holding performance back.
The path beyond cost-based pricing
Moving beyond cost-based pricing means bringing competitive intelligence, demand modeling, and product-level objectives into pricing decisions. This broader approach gives enterprise retailers a better understanding of customer demand, revenue, and profitability.
Cost and margin requirements continue to serve as financial guardrails throughout. As pricing capabilities develop, retailers can move from fixed markups to automated competitive pricing rules and, eventually, demand-led optimization.
How Competera Contextual AI works alongside cost-based pricing
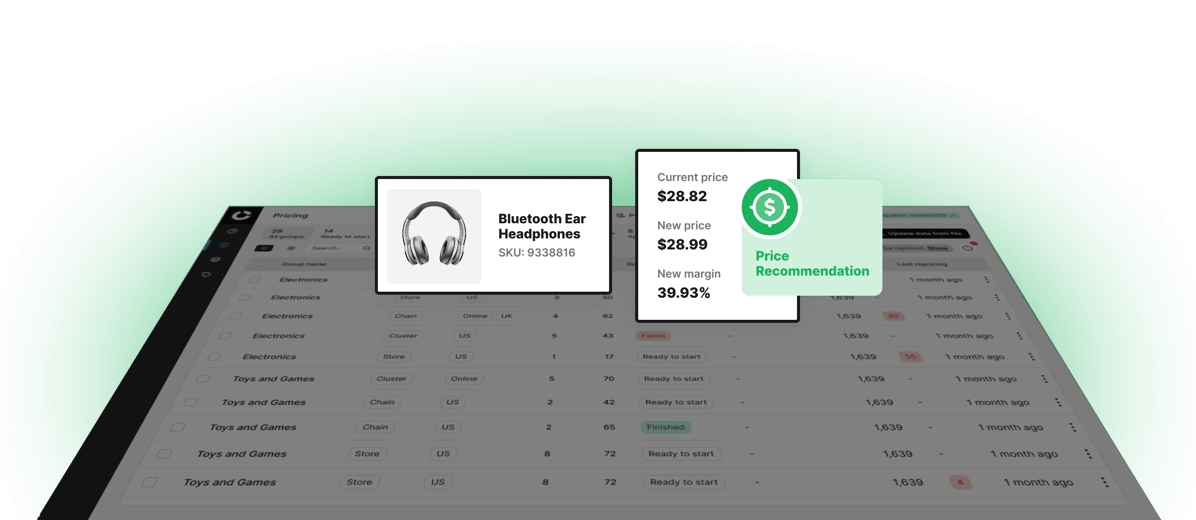
Contextual AI keeps cost as a pricing boundary while recommending prices with demand context. Enterprise retailers can separate products that need competitive prices from those with room to improve margin, while staying within defined financial constraints. Retailers using the Competera Pricing Platform report 3–7% revenue growth and a 2–5 percentage point margin improvement.
Enforcing margin floors automatically
Category managers and commercial leaders can define margin requirements across products, categories, and store clusters. Competera enforces these constraints during repricing, reducing manual checks while keeping recommendations aligned with financial objectives.
For example, a category manager can set a minimum margin requirement for an assortment while allowing different pricing strategies for high-visibility and less price-sensitive products.
Optimizing above the margin floor with demand modeling
Competera evaluates whether a price change supports the retailer's commercial objectives before determining how far the price should move. The engine reads more than 20 demand-driving factors, including:
- Price elasticity
- Inventory health
- Seasonality and promotional activity
- Product lifecycle
- Cross-product relationships
- Competitor movements
That context separates products a formula treats as identical. Two items with the same cost and markup would receive the same cost-plus price, even if their inventory conditions and commercial roles differ. Contextual AI evaluates those differences to show where separate pricing strategies would produce better outcomes.
What-if simulation to validate pricing above cost
Enterprise retailers can compare projected outcomes before implementing price changes. Within the Competera Pricing Platform, commercial leaders can see how alternative pricing scenarios are likely to affect sales volume, revenue, and margin over 1–12 weeks, with probability ratings for each scenario.
These comparisons help decision-makers weigh the trade-offs between protecting margin, maintaining competitive positioning, and pursuing revenue growth, and review proposed prices against financial guardrails before approval.
Conclusion
Cost-based pricing provides a practical starting point for calculating selling prices and defining financial requirements. Its greatest value comes when it is used as a constraint within broader demand-led or competitive pricing strategies, keeping financial discipline while leaving room to respond to the market.
For enterprise retailers, demand modeling adds the context needed to evaluate prices across products with different commercial roles, customer responses, and competitive pressures, leading to more precise and profitable pricing decisions.
Get in touch to see how Competera applies these financial controls alongside contextual demand modeling and pricing simulations across large assortments.
FAQ
What is cost-based pricing?
Cost-based pricing sets a selling price by adding a markup or target return to a product's cost.
What are the three types of cost-based pricing?
The three types of cost-based pricing are cost-plus pricing, markup pricing, and target return pricing.
What is the cost-based pricing formula?
The basic cost-based pricing formula is Selling price = Unit cost × (1 + Markup rate). To hit a target gross margin instead, use Selling price = Unit cost ÷ (1 − Target gross margin rate).
What is the difference between cost-based pricing and value-based pricing?
Cost-based pricing starts from what a product costs the retailer. Value-based pricing starts from what customers will pay for the product's benefits.
What are the advantages and disadvantages of cost-based pricing?
The main advantages of cost-based pricing are straightforward calculations, consistent markup rules, and clearer cost planning. The disadvantages include limited consideration of customer demand, competitor prices, and willingness to pay.
When should a business use cost-based pricing?
A business can use cost-based pricing when costs are measurable and it needs an initial selling price or a financial reference point, such as a margin floor.
How is cost-based pricing used in retail?
Retailers use cost-based pricing to set baseline prices on low-visibility items and new products, and to define margin floors across the assortment.