
Price variance is the difference between the price you planned to charge or pay and the price you actually got or paid, multiplied by the units involved. This guide covers what price variance is, how to calculate price variance for sales, purchases, and materials, and how retailers use it to keep pricing on plan.
Key takeaways
- Price variance is the difference between the expected price and the one you actually got (or paid).
- Price variance = (actual price − standard price) × quantity. Whether a positive result is favorable depends on whether you are looking at revenue or cost.
- Sales price variance covers what you sell for; purchase price variance covers what you pay for finished products; materials price variance covers what you pay for production inputs.
- Purchase price variance adjusts the cost of goods sold and, in some cases, inventory value, so it doesn't appear as a separate expense line.
- For retailers, repeated unfavorable sales price variance is a signal to revisit the pricing plan, often its promotional programs or the competitive data behind it.
What is price variance?
Price variance shows how far a price moved from what you expected. In cost accounting, the general variance definition is the gap between a planned figure and the actual result; price variance applies that idea to prices.
The first step is to set a baseline, such as a standard purchase cost or a budgeted selling price. Then compare it with what final sales figures or supplier invoices show. Multiplying the difference by the number of units involved turns a per-item deviation into a dollar figure someone can act on. The price variance formula is:
Price variance = (Actual price − Standard price) × Quantity
That multiplication is the real strength of the metric. The same five-cent gap would barely register on a slow-moving specialty item but could consume a week of margin on a top-selling staple. Retailers apply the calculation to both sides of the business: what they charge shoppers and what they pay suppliers.
Favorable vs. unfavorable price variance
Whether a variance is good news depends on which side of the ledger it sits on. On the sales side, selling above the planned price is favorable and selling below it is unfavorable. On the cost side the logic flips: paying less than expected is favorable, and paying more is unfavorable. Because both use the same formula, check the sign conventions in your ERP before comparing numbers across teams.
Variance type |
Favorable when |
Unfavorable when |
Example |
Typical cause |
Sales price variance |
Actual selling price above the planned price |
Actual selling price below the planned price |
Planned $4.50, realized $4.30: unfavorable |
Deeper promotions, price matching, late markdowns, stacked discounts |
Purchase price variance (PPV) |
Supplier invoice below standard cost |
Supplier invoice above standard cost |
Standard $62.00, invoiced $66.50: unfavorable |
Supplier increases, freight surcharges, lost volume discount, spot buys |
Materials price variance (MPV) |
Raw materials cost less than the standard price |
Raw materials cost more than the standard price |
Standard $1.80/kg for flour, paid $1.95/kg: unfavorable |
Commodity swings, currency moves, supplier changes, rush orders |
Table 1. Favorable and unfavorable conditions for the three types of price variance.
The three types of price variance
The formula stays the same across all three types, but the reference price changes each time, and so does the team responsible for closing the gap.
Sales price variance
Sales price variance shows the difference between the price you planned to charge and the price shoppers actually paid. The planned price comes from your pricing strategy or category plan before the selling period begins. The realized price is the average price after all promotional coupons, loyalty discounts, markdowns, and price matches. The sales price variance formula, also called the selling price variance formula, is:
Sales price variance = (Actual price − Planned price) × Units sold
A positive result is favorable here. Pricing and category teams own this number, since every discount decision and competitor reaction feeds into it. A favorable result still deserves a second look: pricing well above plan can push shoppers to trade down or switch to a cheaper alternative, which is why price elasticity matters.
Purchase price variance (PPV)
Purchase price variance applies when a retailer buys finished goods to resell. The reference is the standard cost in the system, usually derived from a supplier agreement, a negotiated price list, last year's average cost, or an internal cost-plus formula. Whenever the supplier's invoice differs from it, the gap becomes PPV. The purchase price variance formula is:
PPV = (Actual purchase price − Standard cost) × Quantity purchased
A positive figure means you paid more than the standard cost, which is unfavorable. Common triggers are supplier increases that reach invoices before the standard is updated, fuel and freight surcharges, lost volume discounts when order sizes shrink, tariff changes, and emergency spot buys after a stockout. Procurement usually owns the number, but the consequences land on the shelf: a cost increase with no change to the shelf price comes straight out of the retailer's margin.
Materials price variance (MPV)
Materials price variance is the production-side counterpart of PPV. It compares what a company actually paid for raw materials and components with the standard price in the bill of materials. The materials price variance formula is:
MPV = (Actual price per unit of material − Standard price per unit) × Actual quantity purchased
For most retailers, exposure to MPV is limited to operations that actually manufacture, such as private-label food production or in-store bakeries. The reading is the same as for PPV: paying above the standard price is unfavorable.
How to calculate price variance: worked examples
Example 1: sales price variance in grocery
A grocery chain plans to sell 2 kg bags of basmati rice at $4.50. Over one week it sells 40,000 bags at an average price of $4.20, because a store-level promotion ran deeper than intended and several regions matched a nearby discounter.
Sales price variance = ($4.20 − $4.50) × 40,000 = −$12,000
The variance is $12,000 unfavorable. On its own, the number shows that there is a problem, not where it comes from. Splitting the data by promotion and region shows which factor drove most of the loss.
Example 2: purchase price variance in home furnishings
A home furnishings retailer carries a solid oak dining chair with a standard cost of $62.00. The supplier passes on higher raw material and freight costs, and the invoice for 1,200 chairs comes in at $66.50 each.
PPV = ($66.50 − $62.00) × 1,200 = $5,400
The PPV is unfavorable because the retailer paid above standard cost. With the shelf price fixed at $149, gross margin per chair drops from 58.4% to 55.4%. The merchant has to weigh that three-point gap against raising the price and risking volume, one of the core trade-offs in how to increase profit margin.
Example 3: sales price variance in health and beauty
A health and beauty retailer plans to sell a vitamin C serum at $32.00 and forecasts 11,000 units in a month. Two planned promotions are cancelled, so the average price rises to $34.10. Meanwhile, a competitor sells a comparable serum at $29.99, and many shoppers follow the lower price: sales stall at 8,000 units.
Sales price variance = ($34.10 − $32.00) × 8,000 = $16,800
The price variance is favorable, but the bigger picture is not. Planned revenue was $352,000 (11,000 × $32.00) and actual revenue was $272,800 (8,000 × $34.10), a shortfall of $79,200. Splitting the gap shows why: the sales volume variance is (8,000 − 11,000) × $32.00 = −$96,000, which more than wipes out the +$16,800 price variance.
That's why price variance should always be read alongside volume. A favorable figure can hide significant lost demand, and weighing price against volume is exactly what price optimization models are built to do.
Is purchase price variance an expense?
Purchase price variance is a cost adjustment that reaches the income statement through cost of goods sold, so it doesn't appear as an expense line of its own. Under standard costing, inventory is recorded at standard cost when goods arrive, and the difference between the invoice and the standard is posted to a PPV account. Depending on accounting policy, that balance is either charged to cost of goods sold for the period or allocated between cost of goods sold and the inventory still on hand.
An unfavorable PPV increases costs, while a favorable one lowers them. Treatment differs between companies, so confirm the policy with your finance team.
Price variance in retail pricing decisions
Sales price variance is especially revealing in retail because it shows what your pricing strategy looks like once it reaches the shelf. Prices are set centrally and then rolled out to thousands of SKUs across hundreds of stores and several channels. Almost every step in that chain is a chance for the actual price to drift from the plan.
What causes unfavorable sales price variance at enterprise scale
At enterprise scale, unfavorable variance rarely has a single cause. Promotions are a frequent culprit, through overlapping offers that stack or discounts that stay live longer than planned. Store-level overrides add up when managers turn a one-off match of a local competitor into a habit. Price zones drift when updates roll out unevenly across regions or between online and physical channels, and markdown timing can do real damage in seasonal categories.
Stale market data often sits underneath these issues: teams react to competitor moves they saw days or weeks late. Structured competitive pricing analysis helps pinpoint the likely causes, and tracking the right pricing KPIs keeps them visible over time.
Using price variance as a pricing performance signal
Variance over a single week is mostly noise, but the same pattern over several weeks becomes a diagnostic. A persistent unfavorable variance in one region usually points to a local execution issue, while the same variance across a whole category suggests the planned price itself was wrong.
As Example 3 showed, favorable variance deserves scrutiny too. Combining variance with price index calculation adds market context, showing whether the gap comes from your realized prices or from the market itself moving.
How Competera helps retailers manage price variance
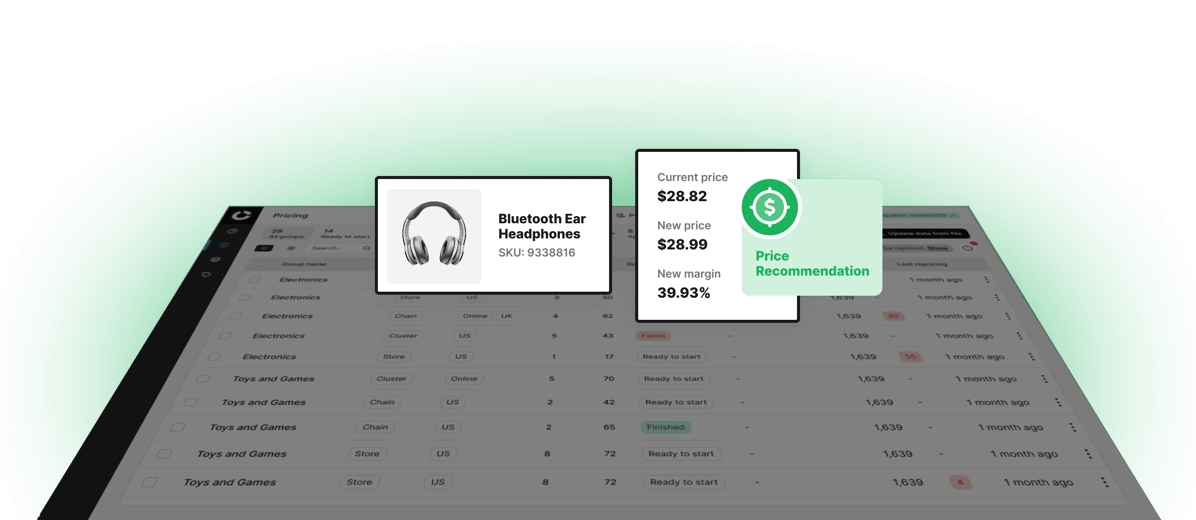
Variance tracking shows when pricing starts to drift from the plan. Fixing it takes two more things: knowing why the price deviated, and pricing logic that accounts for demand. Competera covers both, from market data to price recommendations.
Competitive Data: identifying the source of unfavorable variance
Competera Competitive Data collects competitor prices, promotions, availability, and delivery terms from websites and marketplaces, matches them to each retailer's products, and runs quality checks before delivery, with a 98% average data delivery SLA. The result is an up-to-date, comparable dataset.
Collection can be scheduled as often as every 15 minutes, with data delivered to a dashboard or through integrations such as API and cloud storage. That clear picture helps teams separate market shifts from execution problems, telling a competitor's move apart from a store-level error before they make any adjustments.
Contextual AI: reducing unfavorable variance through demand-aware pricing
Knowing why a price drifted is half the work. The other half is setting prices that hold up when demand shifts, competitors move, and promotions overlap. Competera's Contextual AI, part of Competera Pricing Platform, weighs more than 20 factors when recommending prices, including competitor actions, seasonality, product relationships, and local demand patterns. It supports store-level optimization under central control, and pricing teams review and approve recommendations before they go live.
Because recommendations reflect expected demand, retailers can move beyond reactive dynamic pricing and avoid trading volume for a better-looking price variance. Retailers using the Competera Pricing Platform report 3–7% revenue growth.
Conclusion
Price variance turns the gap between plan and reality into a number teams can manage. The calculation is simple, but the result only becomes useful when you know where it hits the business, what caused it, how volume moved, and whether it will repeat. Retailers need to catch unfavorable variance early, understand its source, and set the next price with enough demand context for the plan to hold.
At scale, that takes reliable market data and demand-aware pricing working together. Talk to an expert to see how Competera helps retailers keep realized prices on plan.
FAQ
What is price variance?
Price variance is the difference between the planned and the actual price, multiplied by the number of units involved. It applies either to what retailers charge customers or to what they pay suppliers.
What is the formula for price variance?
The price variance formula is (actual price − standard price) × quantity. On the sales side a positive result is favorable; on the cost side a positive result is unfavorable.
What is the difference between sales price variance and purchase price variance?
Sales price variance sits on the revenue side and compares planned with actual selling prices. Purchase price variance sits on the cost side and compares the standard cost with what the retailer paid its supplier. Pricing and category teams own the first; procurement owns the second.
What is favorable and unfavorable price variance?
Favorable price variance means results were better than planned; unfavorable means they were worse. Selling above the planned price or buying below the standard cost is favorable, and the opposite is unfavorable.
Is purchase price variance an expense?
Purchase price variance is a variance account that adjusts cost of goods sold and sometimes inventory value. It affects expenses through cost of goods sold rather than appearing as a separate expense line, and the exact treatment depends on company accounting policy.
How do retailers use price variance analysis?
Retailers monitor price variance by category, region, channel, and vendor to catch promotional leakage, store overrides, vendor price increases, and prices falling out of line with competitors. Reading variance alongside volume and margin shows whether pricing execution matches the planned strategy.